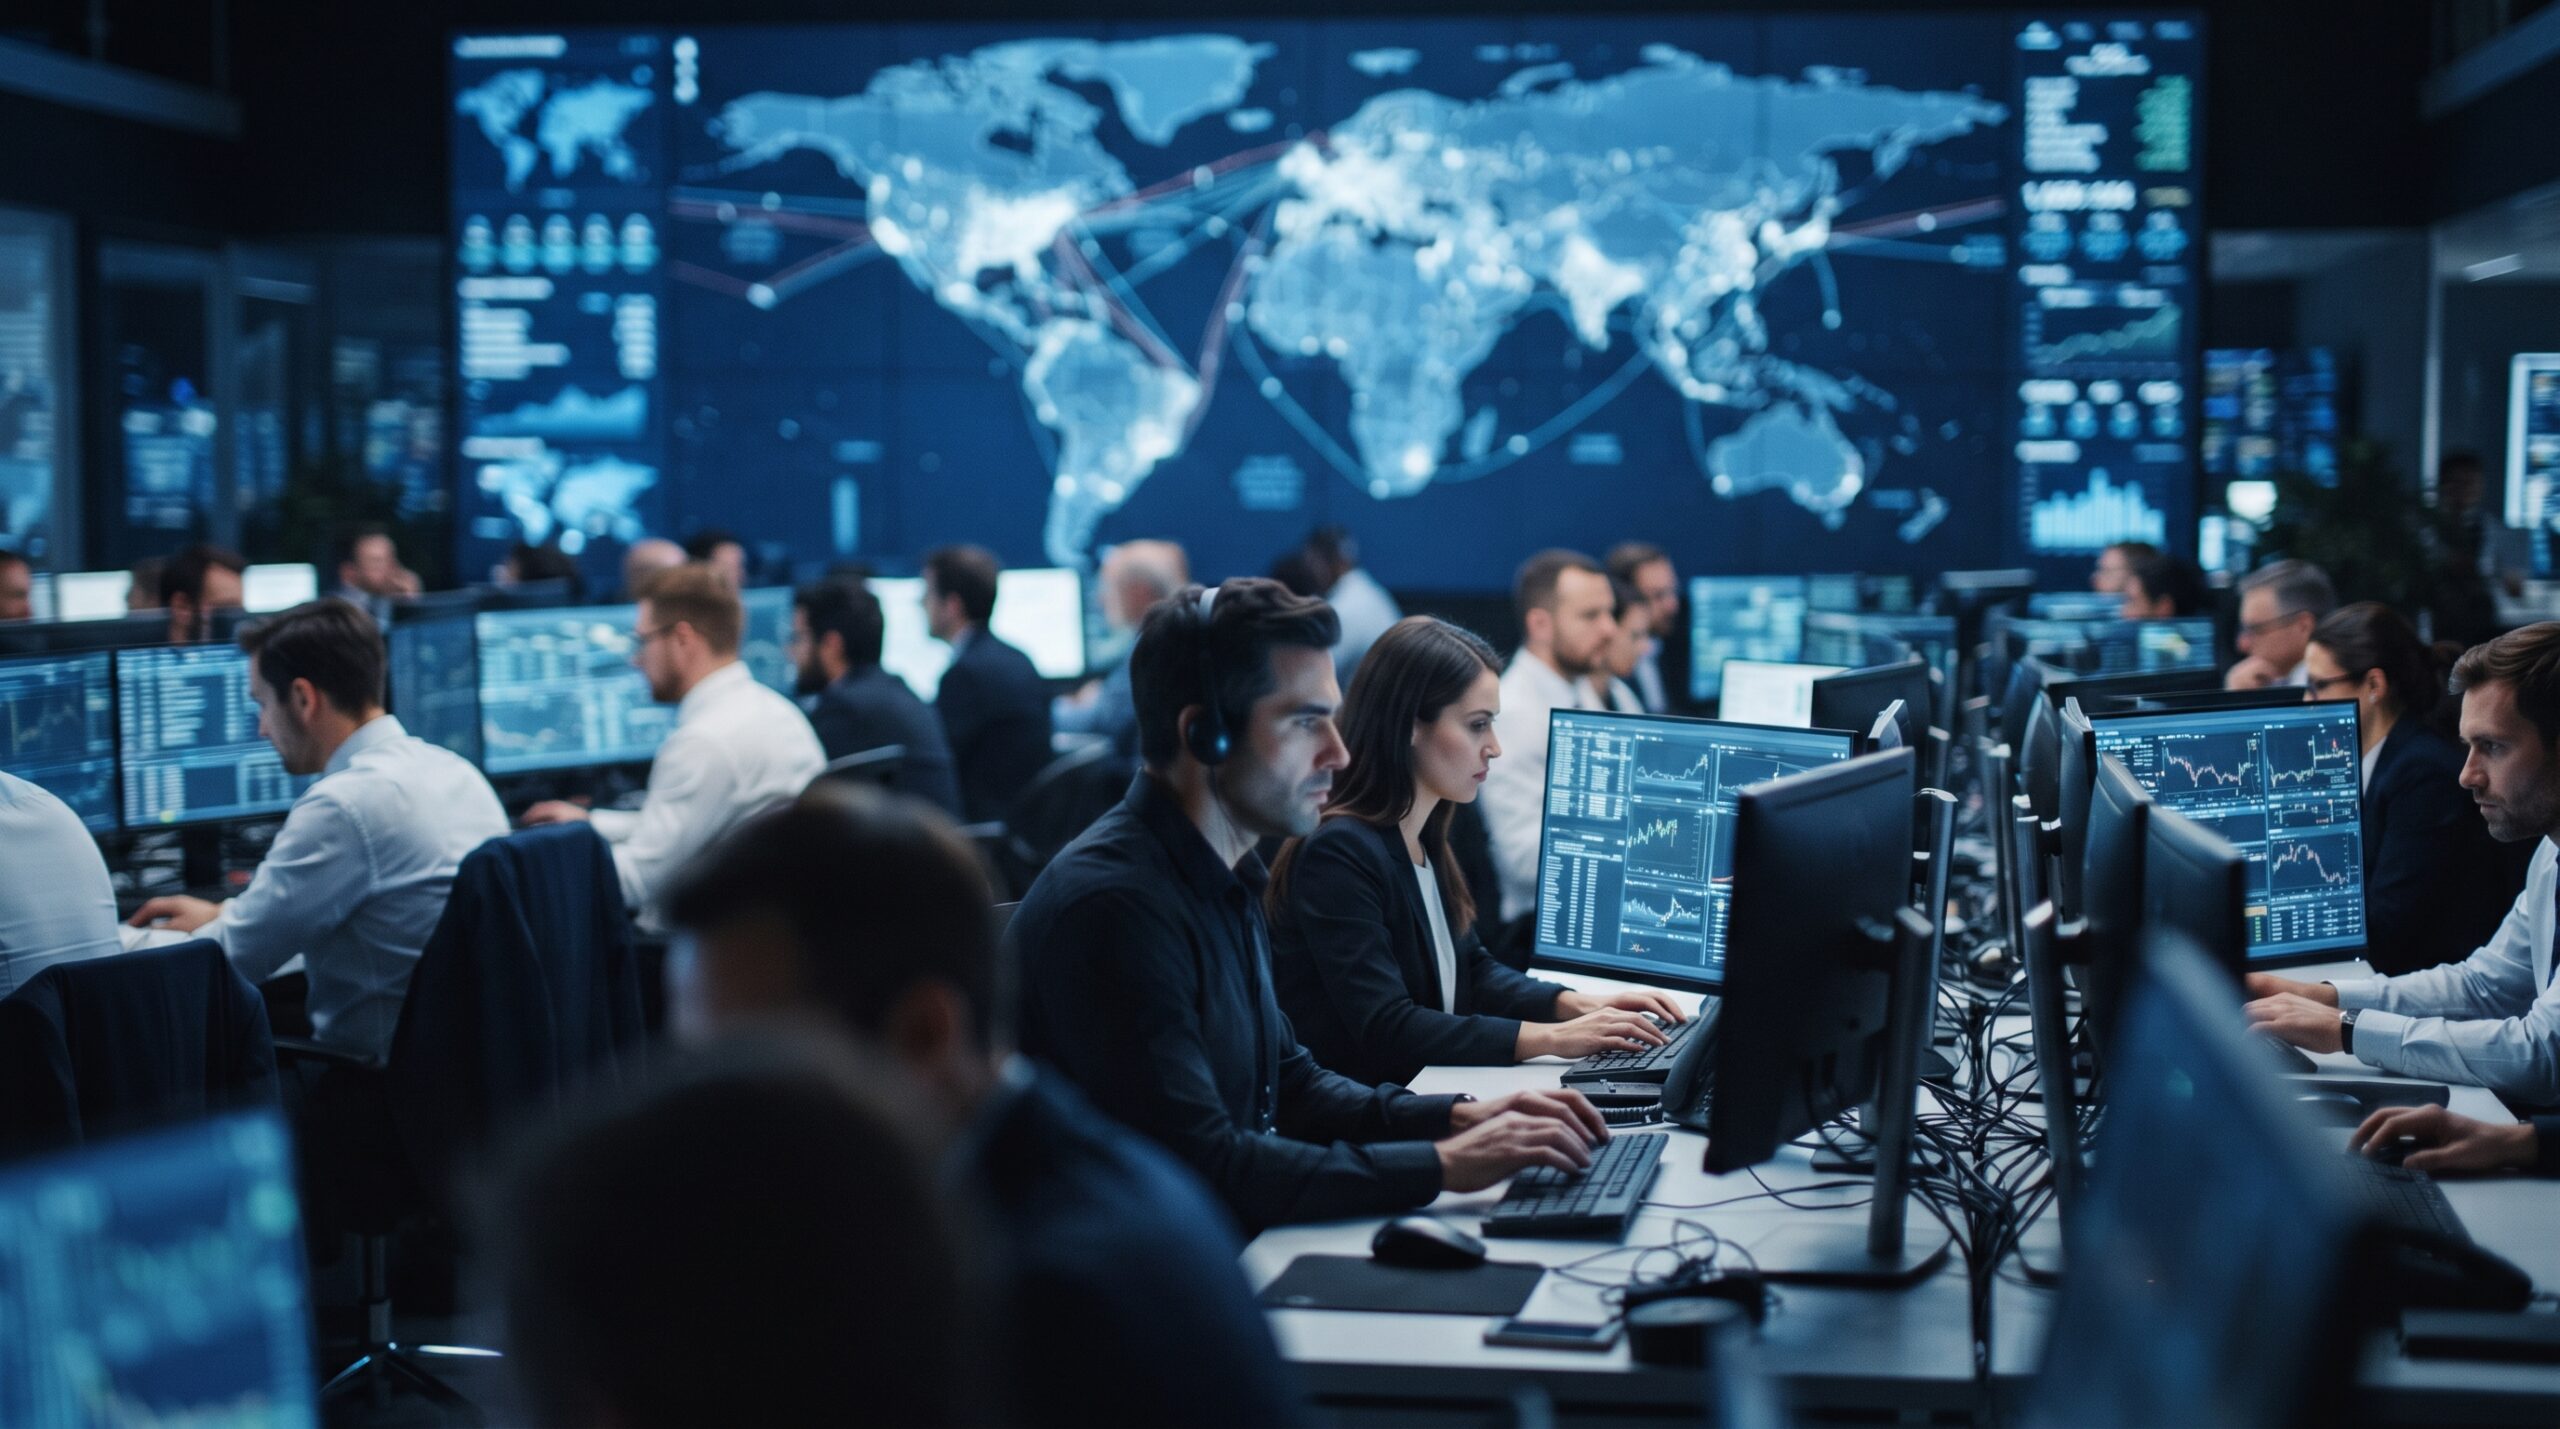
Trade policy used to live in the footnotes of an annual report. Now it can move your portfolio before lunch. A tariff announcement hits the wire, futures reprice, the dollar twitches, and a procurement manager halfway around the world rewrites a shipping plan that was finished yesterday. You do not need to cover every capital in the world to feel the spillover. You only need one supplier, one customer, or one index fund.
Global markets are reacting to shifting trade policies across major economies with a pattern that has become familiar since 2025: sharp moves on headlines, partial recovery when exemptions and deals appear, then a longer grind as companies rebuild supply chains under higher uncertainty. The multilateral trading system did not vanish. It became noisier, more expensive, and harder to forecast.
From Shock Announcements to a Higher Baseline of Uncertainty
The policy turn centered on large tariff actions and the threat of broader reciprocity, with the United States as the primary initiator and other economies responding through retaliation, negotiation, or quiet diversification. Effective tariff rates rose far above the pre-2025 norm even after deals, exemptions, and legal challenges trimmed the most extreme announced levels. Markets learned to trade two variables at once: the statutory rate and the probability that the rate would still exist next quarter.
Legal process added another layer in 2026 when court decisions constrained some authorities used for earlier measures, prompting fresh instruments and temporary across-the-board tools. That sequence—escalate, litigate, redesign—kept trade-policy uncertainty elevated even when average applied rates stabilized below peak rhetoric. For investors, the lesson is blunt. Price the regime, not only the press conference.
Why Equities Flinch First
Equity markets discount expected cash flows. Tariffs raise input costs, complicate demand, and increase the option value of waiting on capital expenditure. Firms with heavier U.S. trade exposure and higher sensitivity to policy uncertainty saw larger valuation swings around major announcement and pause dates, according to research on the 2025 shock window. The rebound after temporary de-escalation was real. So was the residual discount on companies that cannot reroute easily.
How Different Assets Absorb the Same Headline
Currencies react to growth differentials, risk appetite, and safe-haven flows—though “safe haven” behavior has been less automatic when trade shocks originate in the same economy that issues the reserve currency. Bonds price inflation pass-through and the chance that central banks stay tighter for longer if goods prices stick. Commodities split: some industrial metals track manufacturing anxiety, while energy can dominate when geopolitics overlays trade conflict.
Gold and other hedges often firm when policy unpredictability rises and investors question correlation assumptions that worked in calmer decades. Cross-asset moves are rarely clean. A tariff headline that weakens exporters can still lift domestic producers in protected sectors on the same day. Index-level calm can hide violent rotation underneath. If you only watch the benchmark close, you miss the story.
Trade Data Versus Market Drama
Merchandise trade volumes in parts of 2025 proved more resilient than the scariest early forecasts, helped by frontloading, rerouting, and exemptions. That resilience does not mean costs were zero. It means firms adapted faster than static models assumed—and adaptation itself consumes working capital and management time. Markets price both the tariff and the adaptation tax.
Supply Chains Are the Transmission Channel
Companies respond to shifting trade policies long before annual GDP prints catch up. They dual-source, shift final assembly, redesign bills of materials, and renegotiate Incoterms. Some of that shows up as higher inventories and short-term shipping spikes. Some shows up as permanent relocation of capacity toward politically preferred jurisdictions. ASEAN and other connectors have often gained role as alternative nodes when direct lanes between major powers become harder.
None of this is free efficiency. Redundancy raises unit cost. Smaller firms feel it harder than multinationals with legal and logistics depth. When we map exposure for operators, we start with the bill of materials and the customer concentration, not with the speech. If your margin depends on a single preferential path into one large market, you are carrying policy beta whether you hedged the currency or not.
Sector Winners and Losers Are Not Stable
Domestic substitutes in protected markets can enjoy temporary pricing power. Export-heavy manufacturers in targeted economies face margin compression unless they find new buyers. Logistics, customs brokerage, and trade-tech tools see demand for complexity management. Consumer categories with thin margins and hard-to-substitute imports pass costs through unevenly. The map reshuffles every time a major exemption list changes.
Major Economies, Different Playbooks
The United States has treated tariffs as both industrial policy and negotiating leverage, adjusting legal tools when courts intervene. China has mixed countermeasures, selective openness, and accelerated efforts to secure alternative demand and critical inputs. Europe has combined firmness on specific U.S. measures with internal debates about competitiveness and risk of diversion. Canada and Mexico live inside a North American production network where review clauses and rules of origin can matter as much as headline tariff rates.
Elsewhere, governments respond less with mirror tariffs and more with diversification treaties, domestic subsidies, and stockpiling of critical materials. The common thread is strategic hedging. Partners want access where possible and options where not. Markets reward clarity and punish improvisation—yet clarity is scarce when legal bases and political calendars keep shifting.
Inflation and the Central Bank Problem
Tariffs can lift goods inflation in the imposing country while dampening growth through real income and export channels abroad. The size of the effect depends on pass-through, dollar strength, and whether energy shocks arrive at the same time. In 2026, trade friction has not been the only story; geopolitical energy risk has competed for attention on the same screens. Central banks then face an ugly mix: stickier prices and softer momentum. Rate paths become harder to read, and rate-sensitive assets swing with every data print.
A Practical Framework for Investors and Operators
Classify your exposure by revenue geography, input origin, and substitutability. Stress-test margins at a higher effective tariff and at a longer customs delay. Prefer business models that can pass through cost or shift sourcing within two quarters. Treat policy uncertainty as a recurring volatility regime, not a one-off headline. In portfolios, watch factor rotation toward domestic quality and away from pure global cost arbitrage until rules stabilize.
Operators should build a living “trade P&L”: tariff lines, freight differentials, inventory buffers, and compliance headcount. Update it when primary legal authorities change, not only when social media does. Dual-qualify suppliers before you need them. If you sell into the United States or China, maintain scenario packs for escalation, pause, and partial deal—because markets now trade all three as distinct states.
What We Tell Clients Who Want a Single Answer
There is no single answer. There is a process. Reduce single points of failure. Shorten the distance between signal and decision. Do not confuse a relief rally after a pause with a permanent policy floor. The firms that navigate this period best will be boring in the best way: documented sourcing, flexible contracts, and balance sheets that can absorb a quarter of chaos without forced sales.
FAQ
Why do global markets react so strongly to trade policy news?
Tariffs and restrictions change expected costs, demand, and investment timing, so equities, currencies, and bonds reprice quickly when the probability of those changes jumps.
Did global trade collapse after the 2025 tariff shock?
Not in the most extreme sense many feared. Volumes showed resilience through rerouting and exemptions, but costs, uncertainty, and bilateral patterns shifted materially.
Which assets are most sensitive?
Companies with high trade intensity and limited ability to substitute suppliers or customers, plus currencies and sectors tied to targeted goods flows.
How should businesses respond?
Map exposure, dual-source critical inputs, revise pricing clauses, and track legal authorities that underpin tariffs—not only political statements.
Are trade tensions the only driver of market volatility in 2026?
No. Energy geopolitics, growth data, and monetary policy expectations often hit the same week and can dominate short-term moves.
Is this article investment advice?
No. It is analytical commentary for general information. Investment and sourcing decisions require advice tailored to your situation.
Price the Regime, Not the Rumor
Global markets are reacting to shifting trade policies across major economies by treating tariffs, reviews, and court decisions as ongoing inputs to cash-flow forecasts—not as background noise. The headline phase delivers drama. The operating phase delivers higher friction and selective opportunity for those who can adapt supply chains and product mix.
Watch the legal tools, the effective rates, and the rerouting data. Build flexibility before the next announcement, not after. In a fragmented trade system, preparedness compounds faster than prediction.
Blog
This section provides an overview of the blog, showcasing a variety of articles, insights, and resources to inform and inspire readers.
-
The Lasting Influence of Jazz on Global Music Culture
You can go years without putting on a jazz playlist and still hear jazz everywhere.…
-
How Regional Food Traditions Continue to Shape American Identity
Order “barbecue” in one state and you get a vinegar-stained whole hog. Cross a state…
-
The Enduring Beauty of Cambodian Silk Weaving Traditions
You touch a length of hand-woven Cambodian silk, and the fabric instantly feels different from…



Leave a Reply