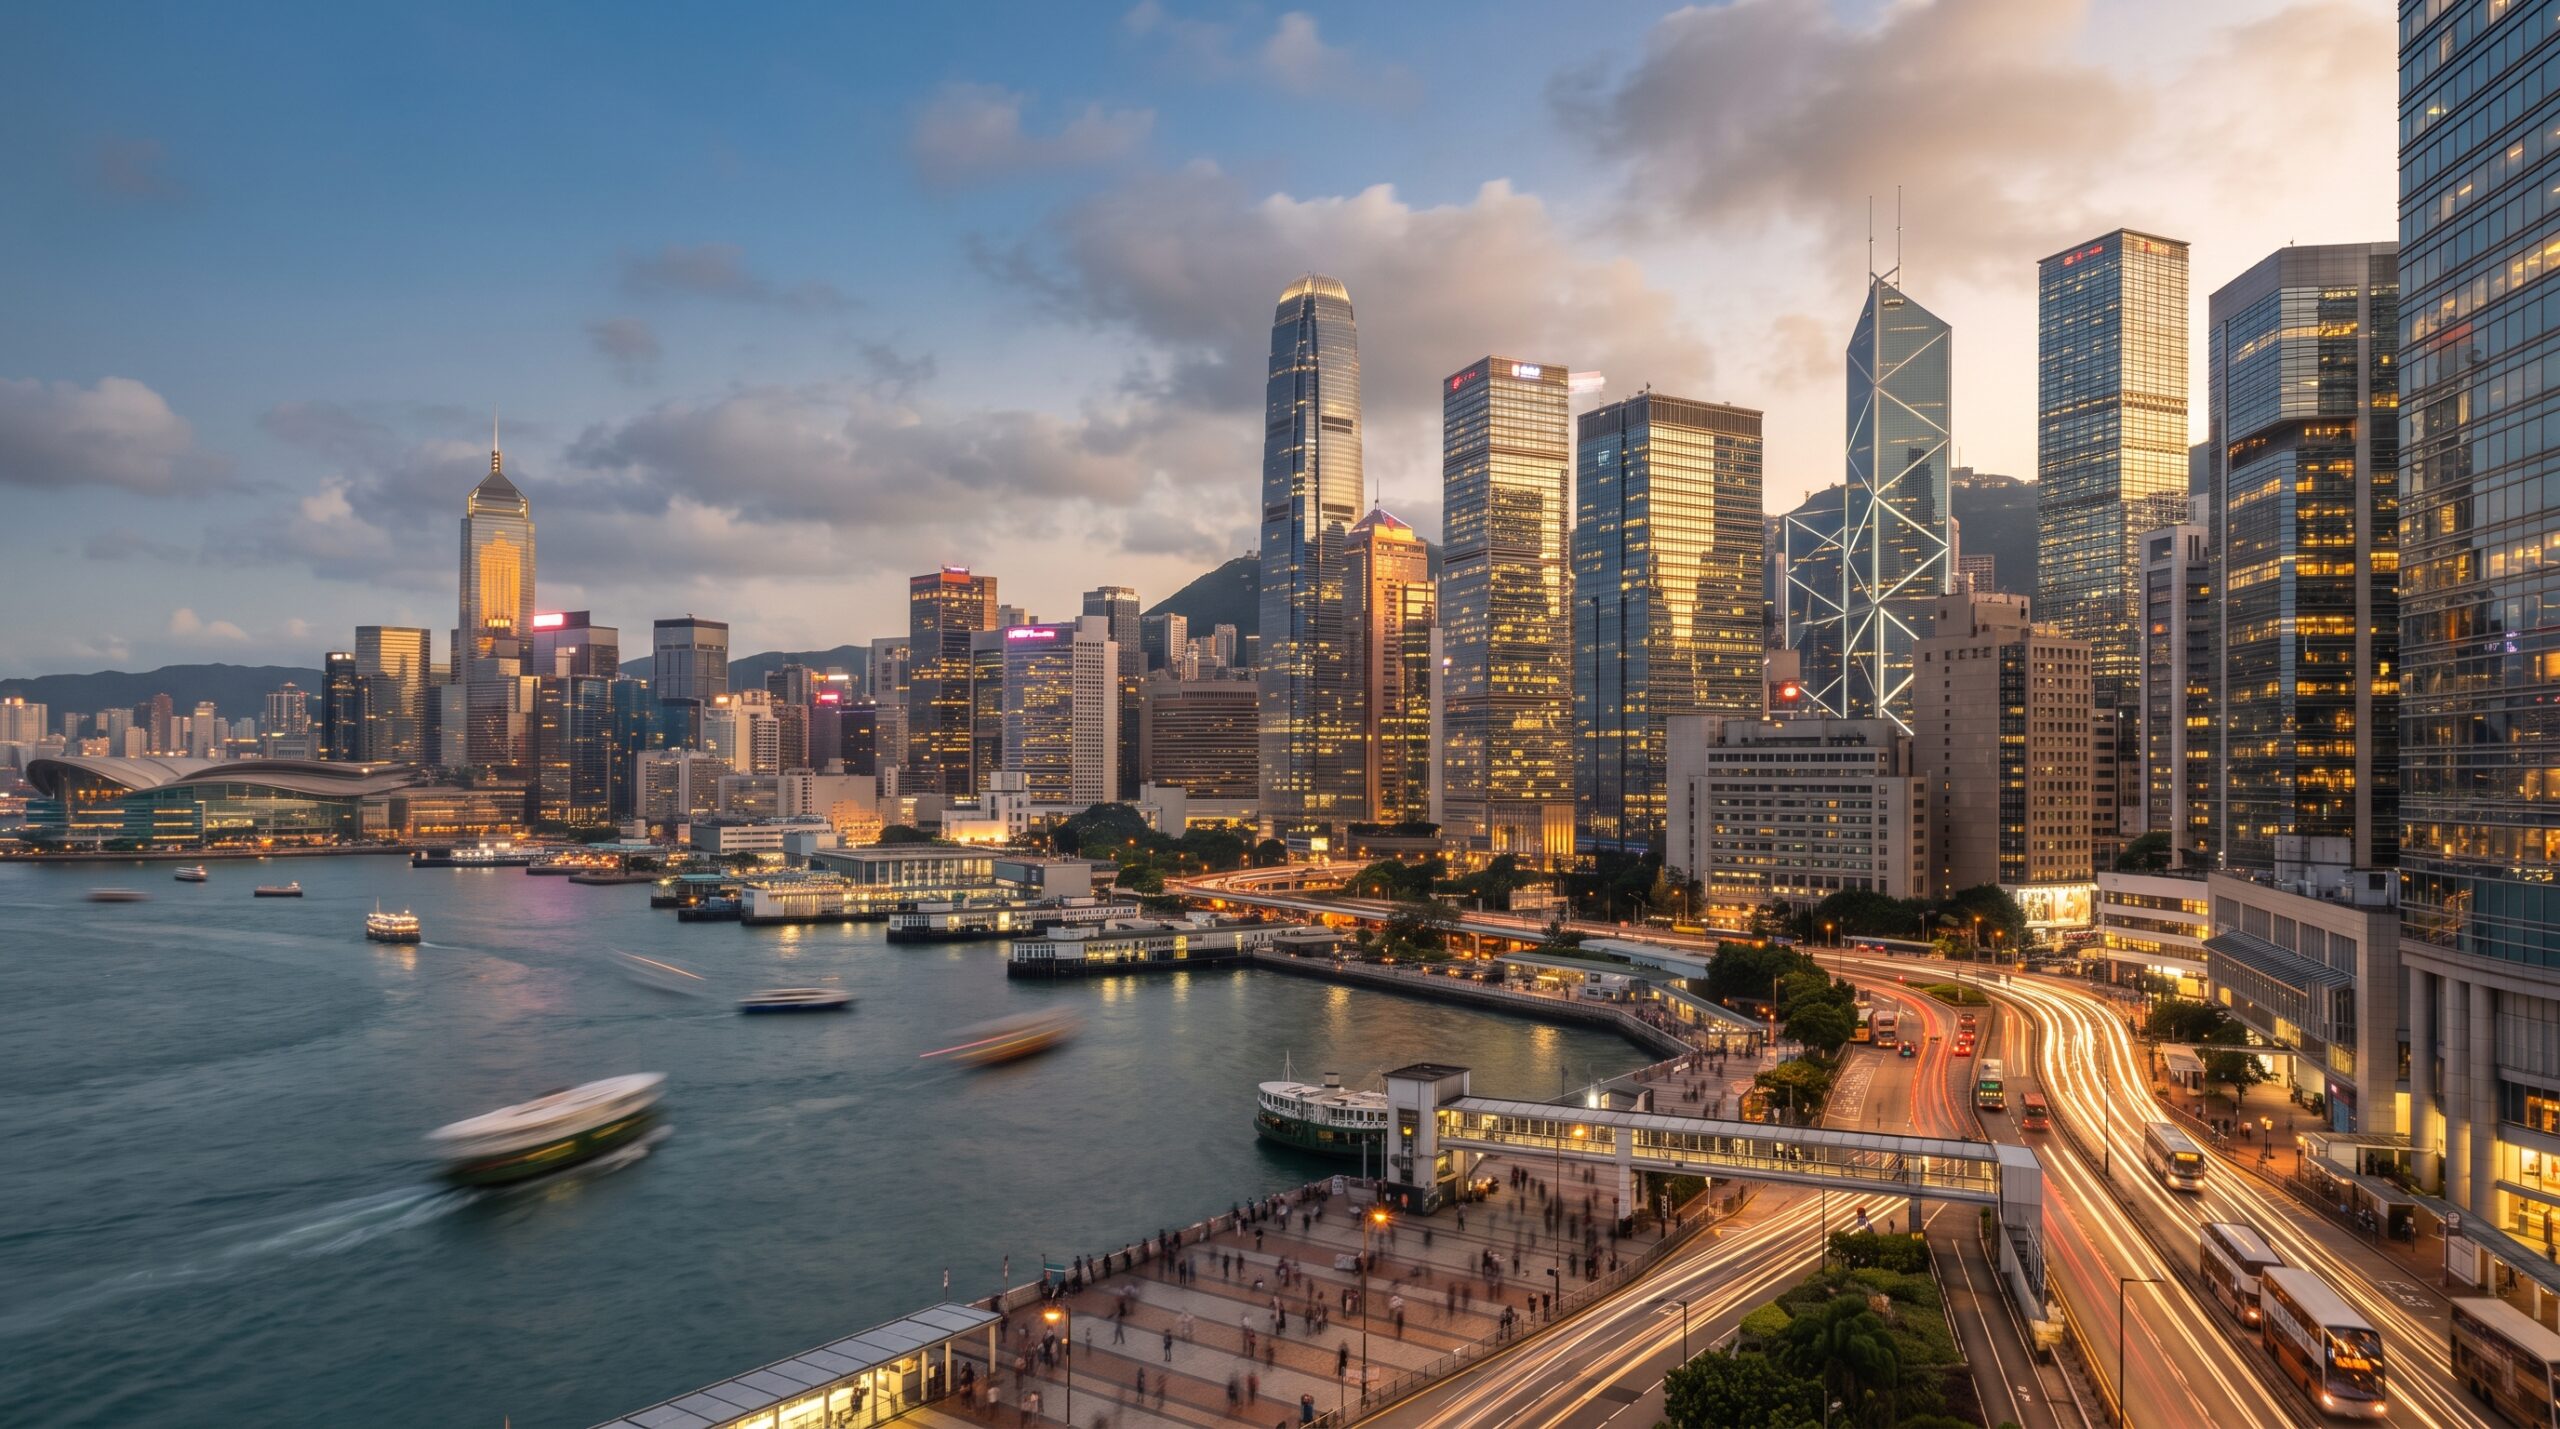
Growth feels scarce when the same developed-market debates recycle every quarter—aging demographics, fiscal strain, and valuations that already price perfection. You can rotate sectors inside familiar indexes and still sense the ceiling. Allocators hunting incremental demand, new listings, and manufacturing scale keep finding themselves back on the same map: Asia.
Capital markets are looking to Asia as a growth engine of the decade because the region concentrates population, trade throughput, and industrial upgrading at a scale few other geographies can match. That thesis is not a blank check. It is a claim about relative growth, capital formation, and corporate opportunity—tempered by policy risk, uneven reform, and the simple fact that “Asia” is not one trade. This article frames how markets are thinking, where the engine is real, and how disciplined investors separate a continent from a slogan.
Why the Growth Narrative Keeps Returning to Asia
Asia holds a large share of the world’s working-age consumers and a still-expanding middle class in several large economies. Supply chains that once ran on pure cost logic now run on cost-plus-resilience logic, which still leaves Asia central even when firms diversify away from single-country concentration. Energy demand, digital adoption, and infrastructure buildouts create multi-year capital expenditure cycles that equity and credit markets try to discount early.
For public markets, the appeal shows up as listings, index weight debates, and active strategies that underweight slow-growth regions in favor of higher nominal GDP trajectories. For private markets, it shows up as venture clusters, manufacturing platforms, and logistics assets tied to regional trade. None of this guarantees excess returns after currency moves and drawdowns. It does explain why research budgets and banker travel schedules keep tilting east.
The Mistake of Treating Asia as a Single Trade
Japan is not Indonesia. India is not Korea. China’s policy cycle is not Vietnam’s FDI boom. A serious Asia allocation is a portfolio of regimes: technology hardware, domestic consumption, commodities linkages, financials tied to credit cycles, and exporters sensitive to the dollar and global goods demand. If your thesis cannot survive contact with country-level detail, it is branding—not analysis.
Where Capital Is Actually Looking for Engines
India draws attention for scale, demographics, and a long runway of formalization and infrastructure needs. Southeast Asia attracts manufacturers and consumer platforms seeking growth and supply-chain alternatives. Korea and Taiwan remain critical nodes in advanced technology hardware even when global electronics cycles turn volatile. Japan periodically re-enters growth conversations when corporate governance reform and shareholder returns gain credibility with global funds.
China remains too large to ignore and too complex to sloganize. Capital markets price both its industrial depth and its regulatory, geopolitical, and property-cycle risks in real time. Some strategies maintain strategic exposure through onshore or offshore channels; others prefer indirect beneficiaries elsewhere in Asia. Either choice should be explicit. “Avoid China” and “all-in China” are both incomplete without a portfolio role and a risk budget.
Markets Beyond Equities
Local-currency bonds, dollar credit, infrastructure debt, and private equity all participate in the Asia growth story differently. Equity captures operating leverage and multiple expansion when sentiment turns. Credit cares about refinancing walls and covenant quality. Currency can erase a correct sector call. Professional capital maps the instrument to the thesis instead of forcing every idea into a single ETF shape.
What Global Liquidity Conditions Do to the Thesis
Asia’s growth engine does not run in a vacuum. U.S. rates, the dollar’s path, and risk appetite in developed markets still set the weather for fund flows into emerging and frontier Asia. When global liquidity tightens, high-beta Asia often feels it quickly—regardless of domestic reform headlines. When liquidity eases, narratives about structural growth regain oxygen and sometimes overshoot.
That linkage is why seasoned allocators pair country research with macro regime checks. A strong domestic reform story can still deliver weak near-term returns if foreign ownership is forced to de-risk. Conversely, mediocre news can ride a wave of global beta. Understanding both layers protects you from confusing a good decade thesis with a good entry month.
Expert Insight From Allocation Practice
We separate “strategic weight” from “tactical risk.” Strategic weight answers whether Asia belongs in a multi-year policy portfolio. Tactical risk answers whether this quarter’s positioning size matches liquidity, elections, and earnings revisions. Mixing the two timelines is how long-term investors become accidental traders—and how traders accidentally marry positions.
Structural Strengths Markets Can Underwrite
Manufacturing ecosystems in parts of Asia remain unmatched for depth of suppliers, logistics, and skilled technical labor. Digital payments and public-tech infrastructure in some countries reduced friction for consumer and SME finance, which equity analysts read as formalization of activity that used to sit outside measured channels. Urbanization and infrastructure pipelines support cement, engineering, and capital-goods demand with multi-year visibility when budgets execute.
Demographics cut both ways. Younger populations can power consumption and labor supply; aging societies in North Asia push automation, healthcare, and fiscal questions. Capital markets price these divergences through sector tilts more than through continent-wide slogans. The growth engine is a set of pistons firing on different schedules.
Corporate Governance as a Return Multiplier
Flows follow not only GDP but also minority shareholder treatment, disclosure quality, and capital discipline. Governance reform can re-rate markets even when headline growth is moderate. Weak governance can trap investors inside fast-growing economies that never translate into free cash flow per share. Underwrite management behavior, not only macro charts.
Risks That Belong in Every Asia Growth Deck
Geopolitics can rewire trade corridors and technology access with little notice. Policy unpredictability—tax, industrial directives, capital controls—changes equity stories overnight. Credit excesses and property cycles have taught repeated lessons about leverage dressed up as growth. Climate and physical risk affect agriculture, insurance, and coastal infrastructure in ways markets still price imperfectly.
Currency volatility deserves its own line item. A correct stock call in local terms can disappoint in hard-currency reports. Hedging costs money and sometimes fails to match the economic exposure you think you have. If you cannot explain your currency stance, you do not fully understand your Asia risk.
Concentration and Liquidity Traps
Narrow leadership inside indexes can make “Asia exposure” a bet on a handful of mega-caps. Small-cap and private opportunities may offer growth with exit risk. Know what you own by look-through weights. Know how long it takes to exit without moving the market against yourself.
How to Engage the Theme Without Outsourcing Your Brain
If you are building a long-term allocation, define the role: growth diversifier, manufacturing upside, or demographic consumption. Choose vehicles that match—broad regional funds, country specialists, sector sleeves, or active managers with on-the-ground research. Read holding lists. Cap single-country risk according to your mandate. Rebalance so winners do not silently become the whole thesis.
If you operate a business, Asia as growth engine may mean customers, suppliers, or competitors more than tickers. Visit operations. Dual-source critical inputs. Track regulatory change the way you track quarterly earnings. Capital markets amplify Asia’s importance; they do not replace operational due diligence.
A Compact Due-Diligence Sequence
Write the country and sector thesis in six lines. List three falsifiers—policy, earnings, or currency. Check liquidity and governance. Size the position for a geopolitical shock, not only for a base case. Review on a calendar. That sequence is how professionals stay with a decade theme without becoming hostages to a hot narrative.
FAQ
Why do capital markets call Asia a growth engine?
Because several Asian economies combine scale, trade integration, industrial capacity, and—in places—favorable demographics relative to slower-growing developed markets.
Is Asia one investment?
No. Outcomes diverge widely by country, sector, governance quality, and currency.
What are the biggest risks?
Geopolitics, policy shifts, credit and property cycles, concentration in index leaders, and currency moves that cut hard-currency returns.
Does China’s role dominate every Asia thesis?
China is central in scale and supply chains, but India, Japan, Korea, Taiwan, and Southeast Asia each carry distinct drivers and risks.
How should long-term investors approach the theme?
With explicit country limits, vehicle selection tied to the thesis, and a process that separates multi-year strategy from short-term flow noise.
Is this investment advice?
No. It is general market education. All investments can lose value.
Growth Is Regional—Returns Are Specific
Capital markets look to Asia as a growth engine of the decade because scale and industrial dynamism remain hard to replicate elsewhere. Capturing that engine in portfolios requires country discrimination, governance scrutiny, and respect for global liquidity and geopolitics. The map is compelling. The fine print decides results.
Refine your Asia thesis to the countries and sectors you can actually monitor. Size positions for shocks. Let the decade work for a process—not for a slogan. That is how growth narratives become allocations you can defend.


Leave a Reply