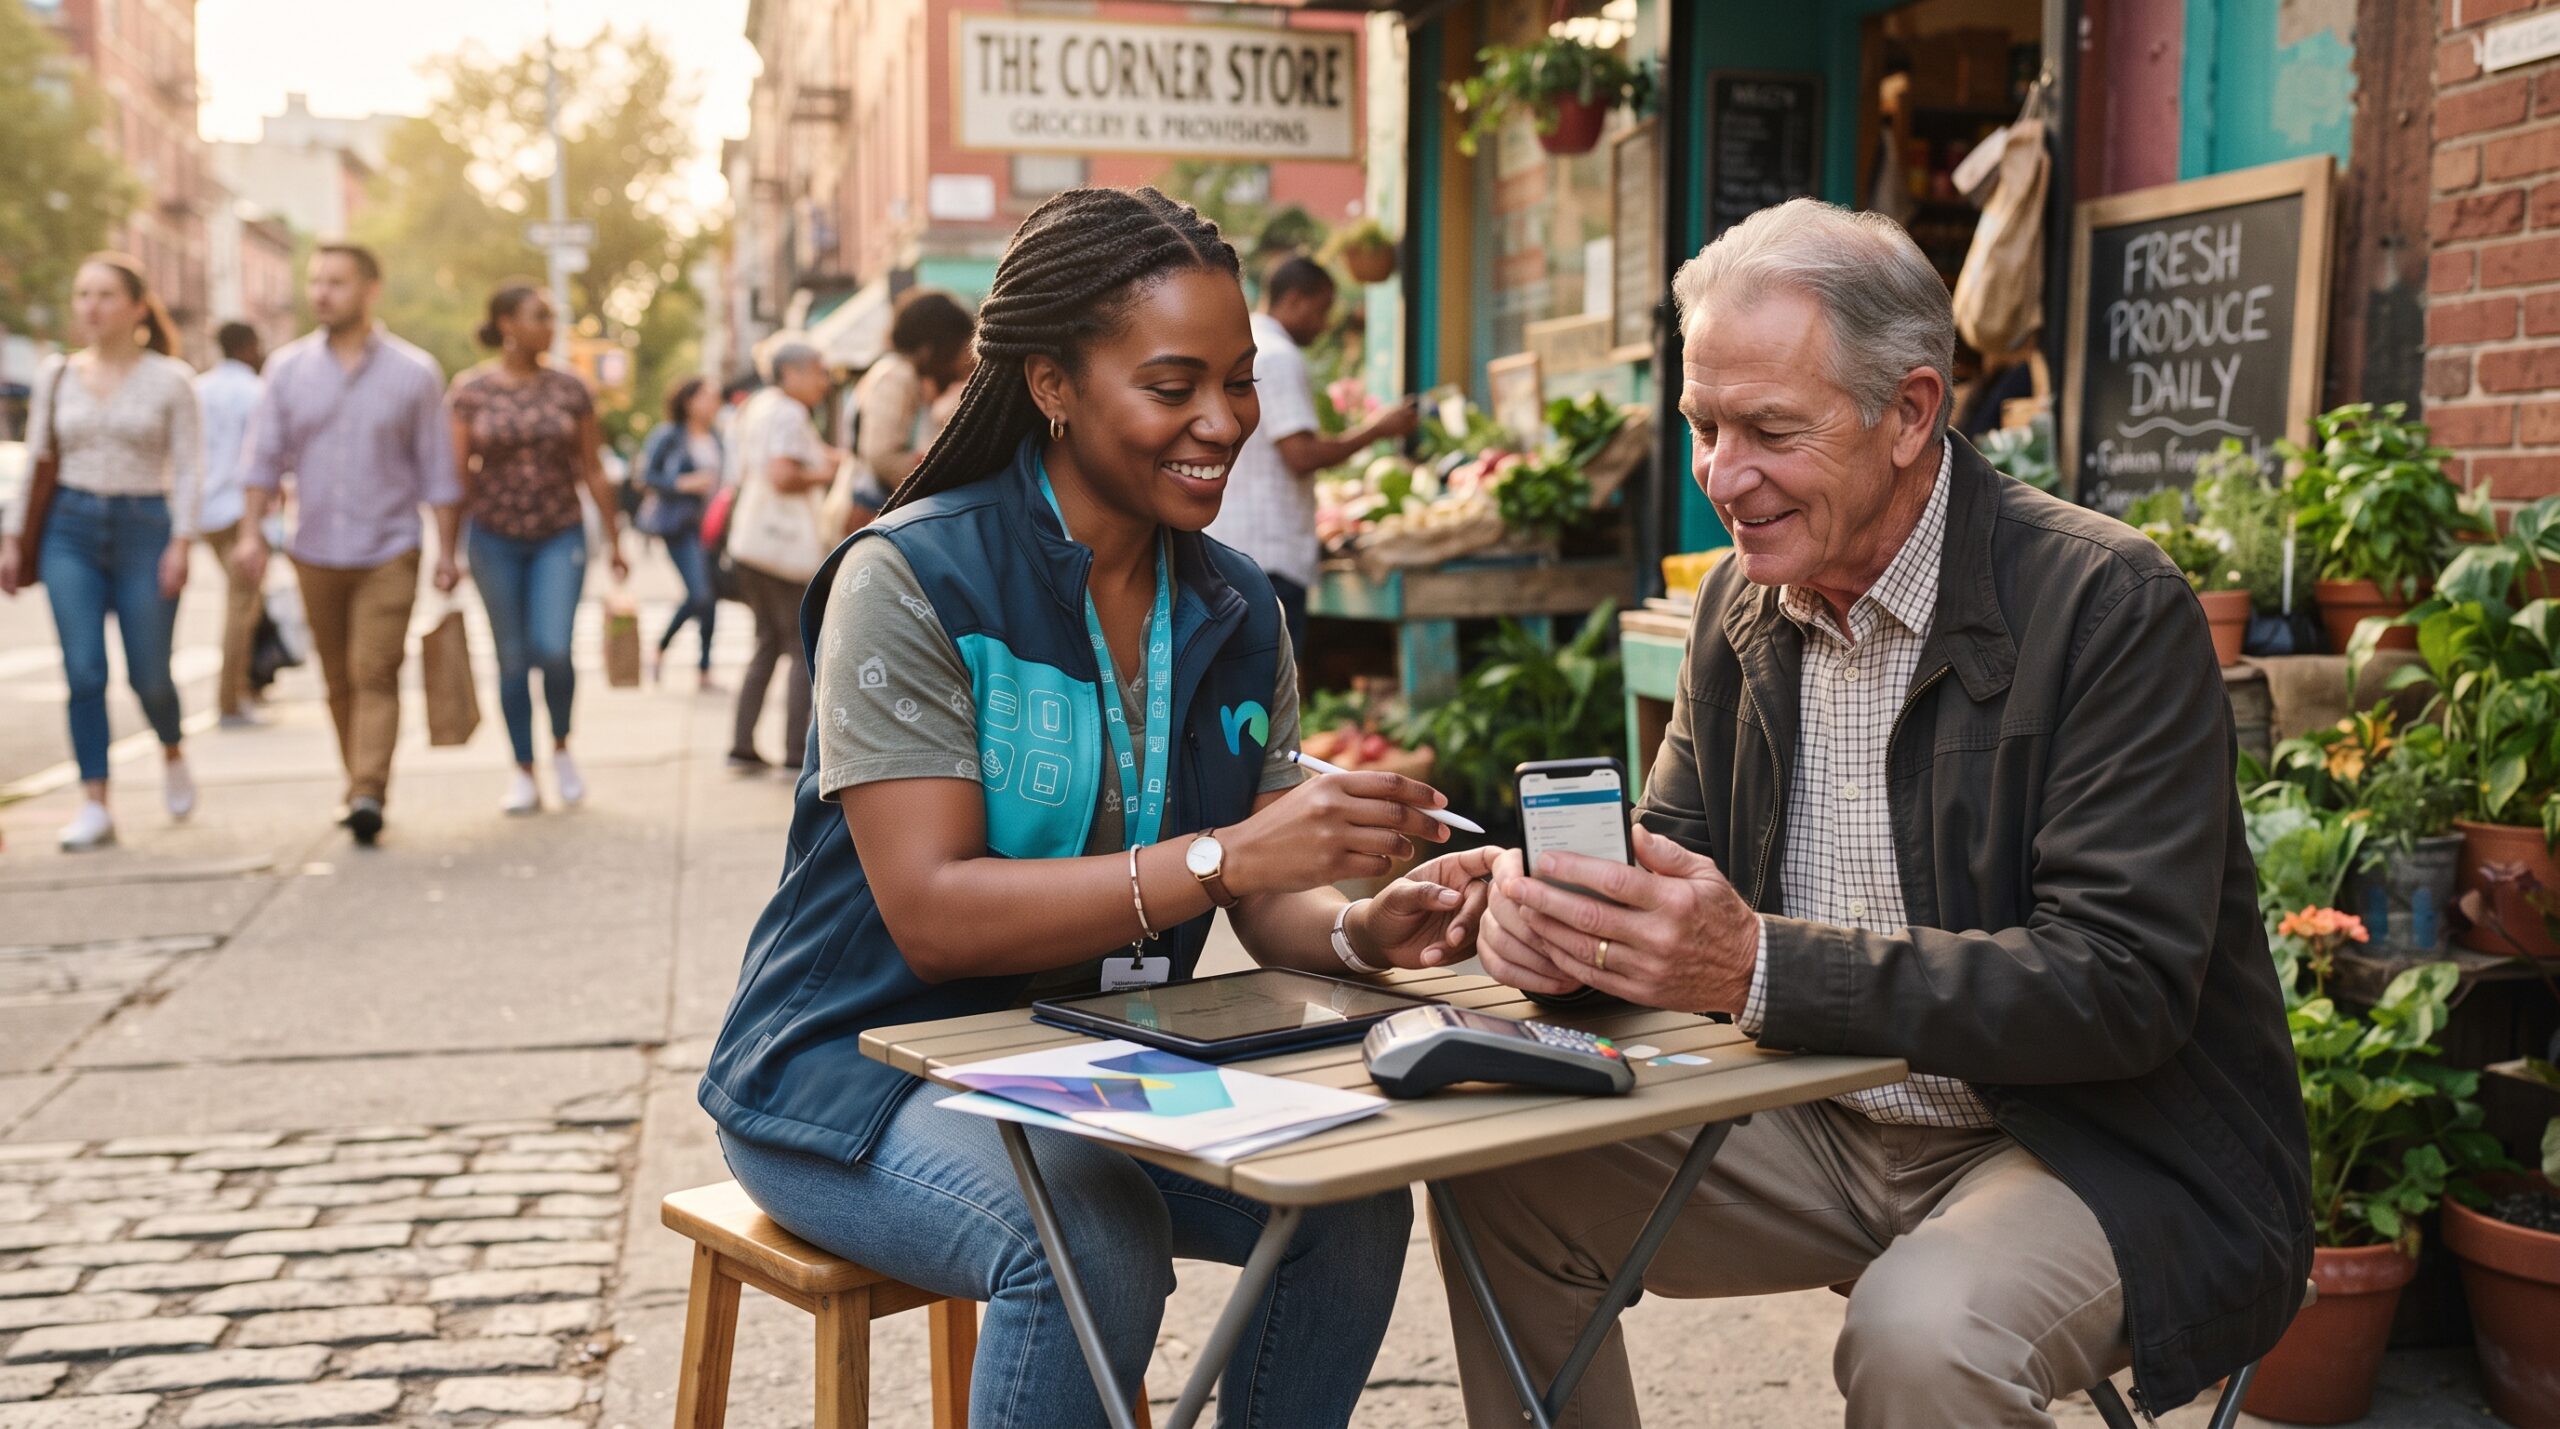
A bank account sounds ordinary until you do not have one. Without a safe place to keep money, every payment becomes cash logistics, every emergency becomes a favor network, and every government transfer becomes a scavenger hunt. You already know people who lose hours traveling to pay a bill that a basic account could settle in minutes.
Financial inclusion efforts expand access to banking services nationwide when policy, technology, and private distribution work together to reach households and small firms that traditional branches skipped. Inclusion is not a slogan about apps. It is measurable use: accounts people can open, trust, and afford—then savings, payments, credit, and insurance that fit real incomes. Done well, it raises resilience. Done carelessly, it can push weak consumers into fees and debt they do not understand.
What Financial Inclusion Really Measures
Inclusion means adults and businesses can access useful, affordable financial products delivered responsibly. An account that sits unused because cash-out points are far away or fees eat small balances is a thin victory. Researchers and central banks increasingly track not only account ownership but frequency of use, digital payment adoption, and whether credit is productive rather than purely extractive.
Nationwide expansion usually combines identification systems, agent networks, mobile channels, and simpler product rules. The aim is to lower the fixed cost of serving rural districts and urban informal workers. When those costs fall, institutions can profitably serve thinner wallets—if consumer protection keeps pace.
Access Is Not the Same as Well-Being
A loan can fund a stall’s inventory or trap a household in rollovers. Inclusion policy that celebrates only origination volumes misses repayment stress and complaint patterns. The right scorecard includes usage, cost transparency, fraud rates, and resolution times when something goes wrong.
The Building Blocks Behind Nationwide Reach
Reliable identity verification is foundational. Where people lack formal ID, account opening stalls or migrates into weak workarounds. Tiered know-your-customer rules can let low-balance accounts open with lighter documentation while higher limits require stronger checks. That balance is delicate: too tight and the poor stay excluded; too loose and fraud rises.
Agent banking and retail partnerships put human help near where people already shop. Mobile money and bank apps reduce travel for those with phones and coverage. Interoperable payment systems let wages and merchant payments move across providers instead of locking users into islands. Each layer only works if network uptime and cash liquidity at agents hold on peak days—salary week, festival seasons, disaster relief periods.
Expert Insight From Field Rollouts
In implementation reviews, the quiet failure point is often agent cash management, not the software demo. Users abandon channels that cannot pay out when needed. Nationwide inclusion is an operations problem as much as a product problem.
Digital Channels Widen the Door—and Leave Some Outside
Smartphones and low-cost data plans accelerated account usage for younger and urban populations. Instant payments turn small merchants into formal acceptors of digital value. Government disbursements into accounts can pull first-time users into the system when cash-out and spending options are nearby.
Digital exclusion remains real. Older adults, people with low literacy, and communities with weak connectivity need assisted models—voice interfaces, simplified UIs, and agents who explain fees without upselling harmful credit. A purely app-first strategy can widen gaps even as national statistics look better. Hybrid design is not nostalgia; it is coverage.
Hypothetical User Journey
A seasonal worker receives wages into a basic account, pays school fees digitally, and saves small amounts automatically. That is inclusion working. The same worker, nudged into a high-cost microloan after a delayed harvest, may appear in the “credit access” metric while household stress rises. Product design and sales incentives decide which story dominates.
Credit, Savings, and Insurance: The Next Rungs
Once payments work, the deeper inclusion agenda is safe savings and appropriately underwritten credit. Small-ticket savings tools with clear rules beat opaque “packages.” Credit linked to verified cash flows—inventory, invoices, or stable remittances—tends to perform better than credit sold as a lifestyle upgrade. Insurance for health shocks or crop stress can protect gains, yet claims processes must be simple or trust collapses after the first denied case.
Financial education helps when it is timely and specific: how fees work, how to dispute a transaction, what a late payment does to future pricing. Generic posters change less behavior than in-product warnings and cooling-off periods. Nationwide programs that fund education without fixing product design usually underdeliver.
Consumer Protection as Infrastructure
Fee caps, complaint hotlines, data privacy rules, and fair-collection standards are not anti-innovation décor. They are what make people willing to keep money in the system after a bad experience. Inclusion without protection is a pipeline into cynicism.
What Success Looks Like for Households and Small Firms
Households gain smoother bill payment, reduced theft risk versus pure cash, and better access to remote commerce. Women and marginalized groups often see outsized benefits when accounts are individual rather than mediated only through a household gatekeeper—though social norms can still constrain control in practice. Small firms that accept digital payments build a transaction history that can later support better credit offers.
Local economies benefit when money circulates with less friction and when relief payments reach people quickly after floods or downturns. Banks and fintechs gain new customers with room to grow balances over time. The social return is real when products remain transparent and recourse is credible.
Risks to Keep in View
Over-indebtedness, agent fraud, phishing, identity theft, and exclusion through algorithmic credit scoring errors all travel with digital expansion. Nationwide programs should publish complaint trends and require remediation playbooks. Quiet problems become political problems when they scale.
Practical Moves for Policymakers, Providers, and Users
Policymakers should prioritize interoperable payments, proportionate KYC, agent network quality, and enforceable consumer rights. Providers should design for low-literacy users, test cash-out reliability, and align staff incentives with long-term account health rather than raw loan counts. Employers and municipalities can help by offering electronic wage and benefit options with onboarding support.
If you are a new user, start with a basic account from a regulated institution, enable strong authentication, and learn fee schedules before storing large balances. Treat unsolicited credit offers with skepticism. Keep records of disputes. Inclusion tools work best when you use them deliberately, not because a street agent hurried you.
A Compact National Checklist
Can a first-time user open an account within reasonable distance and documentation rules? Can they cash out predictably? Are fees visible before confirmation? Is there a working complaint channel? Do savings and credit products fit irregular incomes? Affirmative answers describe expansion that lasts.
FAQ
What is financial inclusion?
Broad access to useful, affordable financial services—payments, savings, credit, insurance—delivered responsibly to individuals and businesses.
Why expand banking access nationwide?
To reduce cash friction, improve delivery of wages and public transfers, support small enterprise, and strengthen household resilience.
Do mobile apps alone solve inclusion?
No. Connectivity gaps, literacy, agent support, and consumer protection still determine whether people can use services safely.
What is a major risk of rapid inclusion?
Over-selling high-cost credit, fraud, and loss of trust when problems lack fast redress.
How can first-time users protect themselves?
Use regulated providers, understand fees, secure logins, start with small balances, and avoid rushed borrowing.
Is this financial advice?
No. It is general public education. Product rules and regulations vary by country.
Access Matters When It Becomes Daily Practice
Financial inclusion efforts expand access to banking services nationwide when identity systems, agents, digital rails, and consumer protection make accounts usable for ordinary lives—not only for statistics. The promise is resilience and participation. The hazard is fee-heavy products and debt that outruns understanding.
Judge programs by usage quality, reliability at the cash-out point, and fair treatment when errors happen. If you are building or using these services, demand clarity over hype. Inclusion is real when the last mile works on an ordinary Tuesday.
Blog
This section provides an overview of the blog, showcasing a variety of articles, insights, and resources to inform and inspire readers.
-
The Lasting Influence of Jazz on Global Music Culture
You can go years without putting on a jazz playlist and still hear jazz everywhere.…
-
How Regional Food Traditions Continue to Shape American Identity
Order “barbecue” in one state and you get a vinegar-stained whole hog. Cross a state…
-
The Enduring Beauty of Cambodian Silk Weaving Traditions
You touch a length of hand-woven Cambodian silk, and the fabric instantly feels different from…



Leave a Reply