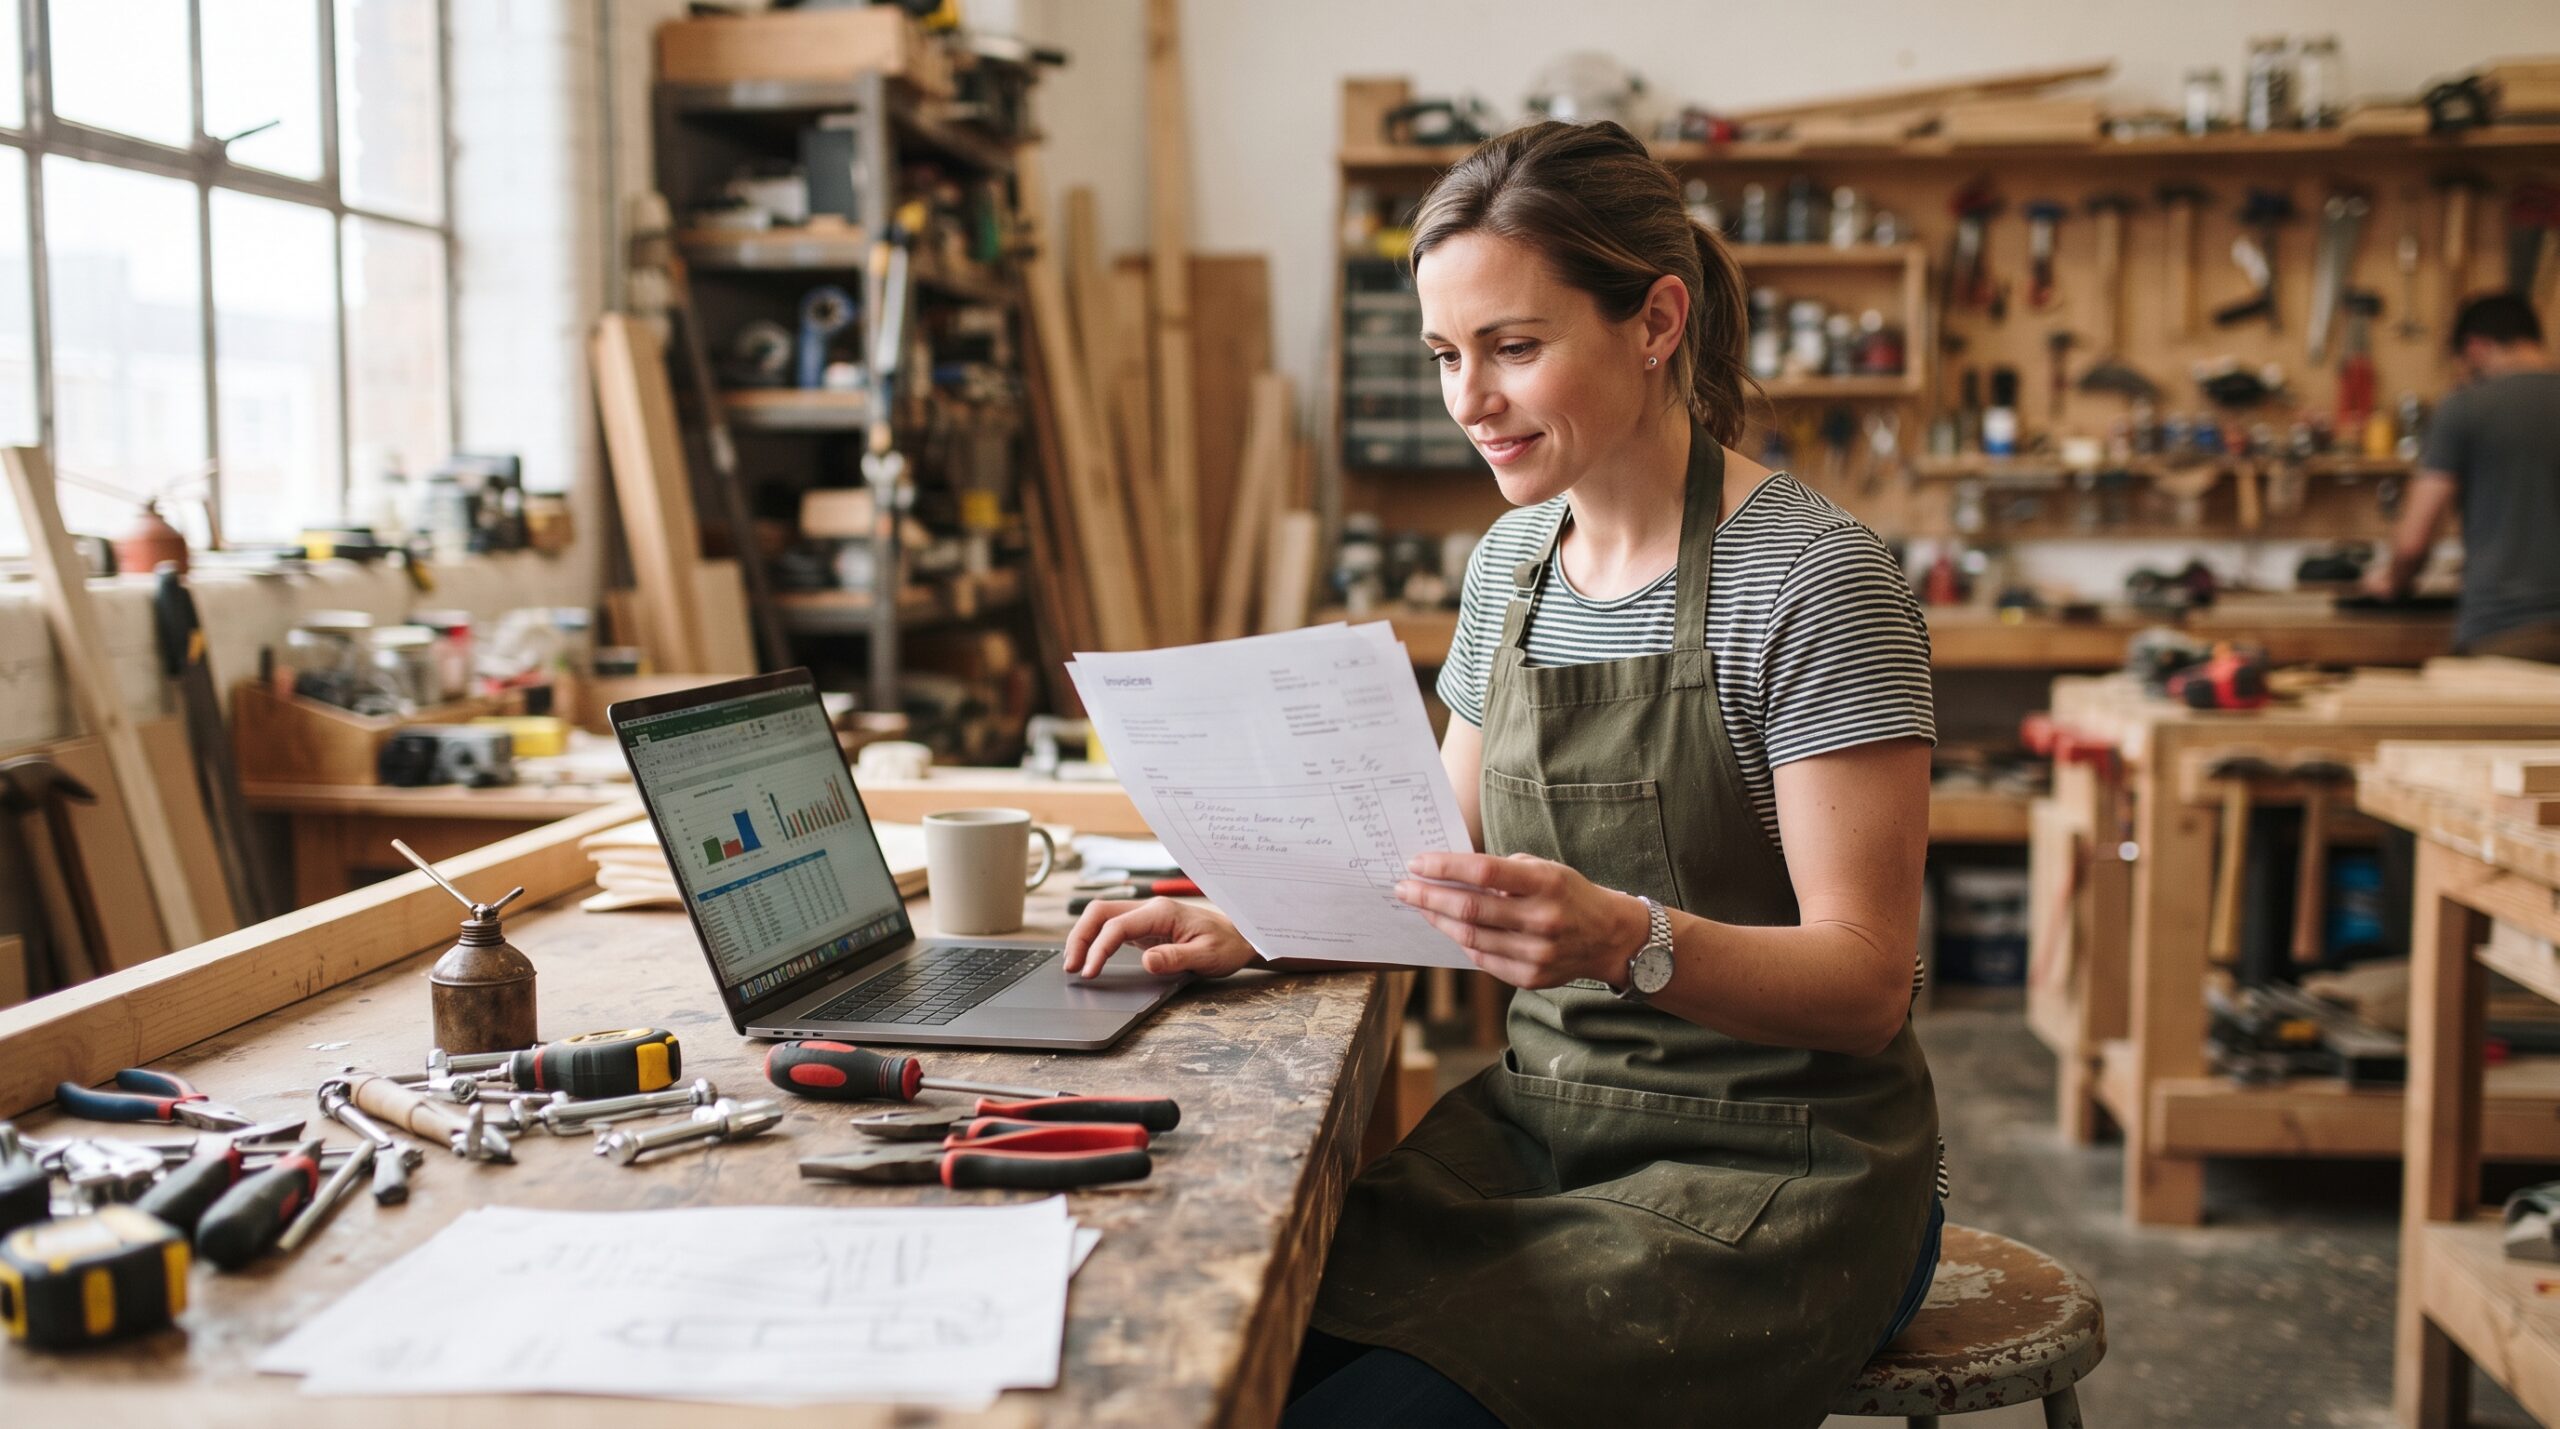
A full order book means little if you cannot buy inventory before delivery day. You know the pattern: sales are rising, suppliers want deposits, payroll arrives every two weeks, and the bank asks for collateral you do not have. Growth stalls not from lack of customers, but from lack of financing timed to the business cycle.
Small and medium enterprises seek better access to capital because traditional credit processes were built for firms with long financial histories, fixed assets, and formal statements. SMEs often operate with thinner documentation, volatile cash flows, and owners who mix household and business finances out of necessity. Closing that gap is an economic priority—SMEs employ large shares of workers in many countries—and a practical daily struggle for owners who simply need working capital that arrives fast enough to matter.
Why SME Finance Remains Harder Than It Looks
Lenders price risk and process cost. A small loan can require almost as much analysis as a larger one, which pushes banks toward bigger clients. Incomplete records make cash-flow assessment difficult. Informal property rights or missing title documents block collateral-based lending even when the business is healthy. Interest rates that look “high” on paper may still fail to cover losses and operating costs for the riskiest segments without guarantees or better data.
Owners experience the problem as rejected applications, slow decisions, or offers that demand personal guarantees on every facility. Some turn to expensive informal credit. Others decline orders to avoid overextending. The economy feels it as fewer hires and weaker supply-chain depth.
Not Every Firm Is Credit Constrained the Same Way
Startups need seed risk capital. Established manufacturers need equipment finance. Exporters need trade facilities. Retailers need inventory revolving lines. Treating “SME finance” as one product guarantees misfit. Diagnosis of the use of funds should come before product shopping.
What “Better Access” Actually Means
Better access is more than a higher approval rate. It includes speed, transparency of fees, repayment schedules matched to cash conversion cycles, and a realistic path to larger facilities as the firm formalizes. A three-month inventory loan that must be repaid before receivables clear is not access—it is a trap.
Digital channels can reduce travel and waiting if underwriting still works. Relationship banking can work if loan officers understand local sectors. The goal is productive finance: capital that raises capacity, stabilizes supply, or bridges receivables—not debt that papers over a failing business model.
Expert Insight From Credit Reviews
When we look at stressed SME files, the common thread is mismatched tenor. Short-term loans funding long-term assets create permanent rollover risk. Match money life to asset life. That single habit prevents a large share of avoidable distress.
Paths SMEs Use When Bank Doors Feel Narrow
Working-capital lines, invoice financing, and purchase-order finance target short cycles when buyers are credible. Equipment leasing can preserve cash versus full upfront purchase. Supplier credit remains the most common informal facility—useful, but concentrated risk if one supplier sets terms. Equity from partners or angel investors dilutes ownership while strengthening balance sheets for firms with high growth potential.
Guarantee schemes and development-finance programs aim to share risk with banks so smaller firms can borrow against cash flow with partial collateral. Results depend on design: slow claims processes undermine lender confidence; loose underwriting without support services can raise defaults. Owners should read guarantee coverage and still prepare strong basic records.
Hypothetical Workshop Scenario
A metal workshop wins a contract requiring new machines and materials. An equipment lease covers the machines; a short receivables facility covers materials after delivery milestones. A single lump-sum personal loan would blur purposes and raise default risk. Structure follows the job.
Formalization and Data: The Quiet Gatekeepers
Banks ask for statements because statements reduce uncertainty. Mobile payment histories, e-invoicing, tax filings, and utility payments can build alternative data trails when banking history is thin. Separating personal and business accounts clarifies cash flow. Simple inventory and receivables tracking makes conversations with lenders shorter and more credible.
Formalization has costs—time, taxes, compliance. It also unlocks facilities informal firms rarely see. Owners should treat bookkeeping as a financing tool, not only as an obligation. A clean six-month record often changes the tone of a credit meeting more than a passionate pitch.
Practical Record Habits That Help
Monthly profit-and-loss even if basic. Separate business wallet or account. Written invoices with buyer details. Supplier contracts where possible. A one-page note on seasonality. These artifacts are small. Their absence is loud.
Policy and Market Reforms That Expand Access
Competition among banks, microfinance institutions, and responsible fintech lenders can widen options if consumer and MSME protection keeps pace. Movable-collateral registries let firms pledge machinery or inventory more effectively where law allows. Credit bureaus that include positive payment history help good borrowers stand out. Fast, fair insolvency processes reduce the dead weight of failed firms and can, over time, lower risk premiums.
Financial literacy programs help only when paired with usable products. Training someone to compare APRs means little if every offer is opaque. Regulators that publish complaint data and enforce disclosure improve market quality. Inclusion without protection repeats old problems on new apps.
What Lenders Can Do Better
Segment products by sector cash cycles. Offer graduated limits that rise with on-time performance. Explain declines with enough detail for firms to improve. Speed decisions on small tickets. Partnership between credit and business-development services often outperforms credit alone for first-time borrowers.
What Owners Can Do This Quarter
Write a short financing plan: amount, purpose, repayment source, and timeline. Clean up account separation and basic books. Approach lenders with a coherent story and evidence, not only urgency. Compare total cost—fees, compulsory savings, insurance add-ons—not only headline rates. Avoid stacking multiple high-cost digital loans to cover a structural gap.
If equity is appropriate, clarify governance before money arrives. If a public guarantee program exists, ask your bank how claims work and what documentation you must maintain. Build relationships before peak season stress. Capital access improves when you look preparable on a quiet day, not only desperate on a deadline.
A Compact Readiness Checklist
Clear use of funds. Repayment mapped to invoices or sales season. Personal and business cash separated. Six months of records. Collateral list or guarantee pathway. Exit plan if the order slips. Complete that list before you sign.
FAQ
Why do SMEs struggle to get capital?
Higher perceived risk, thinner documentation, limited collateral, and high process costs relative to small loan sizes.
What types of financing fit SMEs best?
It depends on need: working capital lines, invoice finance, leases, trade facilities, or equity for growth firms—matched to cash-flow timing.
Can digital lenders solve the gap?
They can improve speed and reach, but cost, data use, and over-borrowing risks require careful comparison and regulation.
How does formalization help?
Clearer records and tax compliance improve credit assessment and unlock regulated products informal firms rarely access.
What should I prepare before applying?
Purpose of funds, repayment plan, basic financial records, and documentation of sales or contracts.
Is this personalized financial advice?
No. It is general business education. Seek licensed advisors for specific decisions.
Capital Follows Clarity
Small and medium enterprises seek better access to capital because growth and stability require financing that fits real operating cycles. Banks, policymakers, and fintech channels each hold part of the solution—risk-sharing, better data, fair disclosure, and products designed for smaller tickets. Owners hold the other part: records, separation of funds, and honest matching of debt to purpose.
Tighten your books, define the use of funds, and approach lenders with a repayment map. Better access is not only a policy headline. It is a preparation habit that makes your firm easier to fund when opportunity appears.
Blog
This section provides an overview of the blog, showcasing a variety of articles, insights, and resources to inform and inspire readers.
-
The Lasting Influence of Jazz on Global Music Culture
You can go years without putting on a jazz playlist and still hear jazz everywhere.…
-
How Regional Food Traditions Continue to Shape American Identity
Order “barbecue” in one state and you get a vinegar-stained whole hog. Cross a state…
-
The Enduring Beauty of Cambodian Silk Weaving Traditions
You touch a length of hand-woven Cambodian silk, and the fabric instantly feels different from…



Leave a Reply